Business sale and succession
Selling your business into the right hands.
From the first confidential conversation to receipt of the purchase price. Personally led by Mathias Westerbarkei.
Who we work for
Owner-managed family businesses and shareholders with a significant stake. For you, the sale is a life event, not a portfolio decision.
- Transaction size
From around €1 million to €100 million in enterprise value. Smaller mandates that other M&A advisers turn down are expressly welcome here.
- Industries
Sectors include mechanical engineering, plant engineering, automotive, aerospace, IT, construction and energy. Experience with cross-border transactions in Europe, North America and Asia.
- Region
Rooted in Westphalia and active throughout Germany. International reach through the German M&A association (Bundesverband Mergers & Acquisitions gem. e.V.) and our partner network abroad.
- Typical situations
Succession, strategic sale, preparation for a later sale (exit readiness), sale of a division or subsidiary out of a group (carve-out), sale from the portfolio of a family office.
Two routes, one standard
From €10 million in enterprise value
An individual valuation and a tailored approach to buyers.
Below €10 million in enterprise value
A digital process supported by AI. The same quality, faster and affordable for smaller mid-sized companies too.
At your side
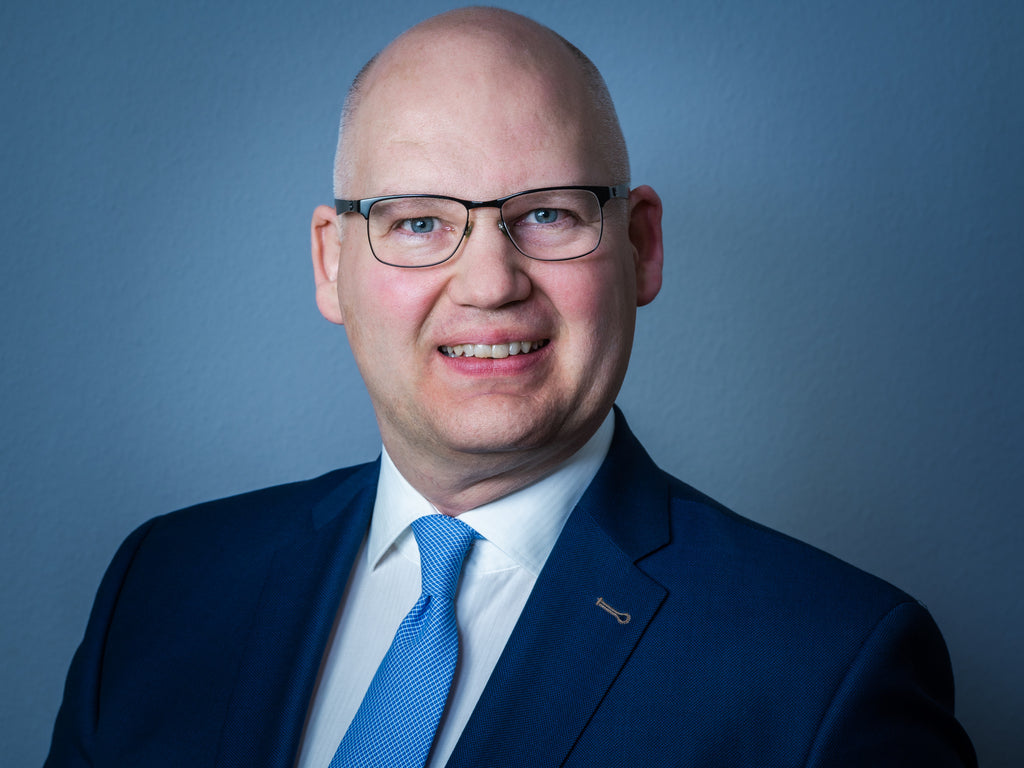
Mathias Westerbarkei, over 25 years of experience in M&A, corporate finance and strategy. 18 years at CLAAS KGaA mbH, most recently Head of Mergers & Acquisitions. There, among other transactions, he was responsible for the sales of CLAAS Fertigungstechnik to MBB Industries AG and of Brötje-Automation to Deutsche Beteiligungs AG.
He then became CFO of DTS IT AG. Since 2017 he has been advising owner-managed companies. From 2023 to 2025 he was also Investment Manager in the family office of the Goldbeck Group.
Member of the Bundesverband Mergers & Acquisitions gem. e.V., valuation working group. Contributor to the standard German reference work “Post Merger Integration” by Gerds and Schewe (5th edition), with a chapter on the Renault Agriculture integration at CLAAS.
We guide your sale from the very first hour to completion. Legal and tax advice comes from the lawyers and tax advisers you appoint. If you wish, we can recommend specialists from our network.
How we work
From the initial consultation to receipt of the purchase price, in five clearly structured phases.
- 01
Initial consultation
Free of charge, confidential and without obligation. We examine whether a sale is the right path for you.
What happens in this phase
- Diagnosis of sale readiness and clarification of who else shares in the decision
- Strategic options, sale concept and type of sale process
- Framework: budget, advisory team, timetable
Questions to ask yourself
If, two years from now, you look out of the window of your former office and a stranger is running your company, what would a successful outcome be for you?
Apart from you, who has to agree in the end for a sale to go ahead?
Are you prepared to stay operationally tied to the business for twelve to eighteen months after completion (closing), or is an immediate clean break a precondition?
- 02
Valuation and preparation
We value your company, prepare the sale documents and define the group of potential buyers.
What happens in this phase
- Indicative valuation using several methods
- Adjustment of the operating result (EBITDA normalisation)
- Setting up and structuring the data room
- Sale story, teaser and detailed information memorandum
- List of potential buyers with clear selection criteria
Questions to ask yourself
Which revenues and margin components depend on particular people or customers, and what happens when you are no longer in the business?
Which issues (contaminated land, legal proceedings, pension obligations, change-of-control clauses) would you examine first if you had to buy your own company?
Which assets held in the company do you want to keep out of the sale, and has taking them out been thought through from a tax perspective?
- 03
Approaching buyers
We approach suitable buyers confidentially, obtain offers and take the best selection into negotiations. You decide who receives information.
What happens in this phase
- Discreet approach and confidentiality agreements
- First written request to the buyers (process letter I) to submit a non-binding indicative offer
- Management presentations and site visits
- Second written request (process letter II) to submit a binding offer
- Comparison of offers by price, structure, certainty of financing, completion risk and strategic fit
Questions to ask yourself
Are there competitors, customers or suppliers who must under no circumstances receive information, not even in anonymised form?
Which buyer profile (strategic buyer, financial investor, family office) would make you personally most uneasy, and why?
What minimum valuation would be the point at which you would stop the process, and has this figure been agreed with the other shareholders?
- 04
Negotiation and the buyer’s due diligence
We support you through the buyer’s review (due diligence), negotiate the sale and purchase agreement and protect your interests up to notarisation.
What happens in this phase
- Exclusivity with a clearly defined term
- Looking after prospective buyers in the data room and answering their questions
- Negotiation of the sale and purchase agreement: purchase price, warranties, performance-based deferred payments (earn-out), where appropriate warranty and indemnity insurance (W&I)
- Insisting on a binding financing commitment before notarisation
- Preparation of the notarisation and all schedules to the sale and purchase agreement
Questions to ask yourself
How far are you prepared to go on warranties, indemnities and liability caps, and do you have a transaction lawyer who will defend your position?
Would you accept a performance-based deferred payment (earn-out), and if so, what percentage and what term would be the maximum?
If the buyer loses its financing shortly before notarisation or tries to push down the valuation with findings from due diligence, how will you respond, and who decides?
- 05
Completion
We guide you through to completion (closing). Shares are only transferred once payment of the purchase price is secured.
What happens in this phase
- Systematic review of all conditions for completion (merger control clearances, shareholder resolutions, bank consents)
- Support with communication to employees, customers and suppliers between notarisation and completion
- Coordination of warranty and indemnity insurance (W&I) and, where needed, an escrow arrangement, through external partners if required
- Advice on preparing the handover phase
Questions to ask yourself
How will communication with employees, customers and suppliers run between notarisation and completion, and who will hold which conversations personally?
What role do you want to take on after completion, and is it fixed in the contract?
Have you clarified with your tax adviser how the purchase price is to flow, and by when this has to be decided?
What we stand for
Three principles without which we do not accept a mandate.
01
Preparation beats speed
You can only run a sale properly once. A process that has visibly been called off is hard to repeat later. That is why we deliberately take our time over the first two phases.
02
A good deal for both sides
We put known risks on the table early, before the buyer’s side finds them. Our aim is a deal after which both sides are still happy to meet for a coffee ten years later.
03
Confidentiality without exception
We never disclose your company’s name without your consent. Every potential buyer signs a confidentiality agreement in advance.
No one finds out until you decide.
Find out more
- Calculate your enterprise valueA first value range based on industry and EBITDA. Free, no registration required.
- Sale Readiness CheckTen questions, around five minutes. How ready for sale is your company, and where would a buyer ask questions?
- Exit readinessIdeally one to three years before the sale: your business becomes worth more and less dependent on you personally.
- For advisers and intermediariesCooperation for tax advisers, auditors and lawyers whose existing clients include succession cases.
More value. Whether you sell or not.
With AI Value Creation we unlock more EBITDA and more enterprise value. Our self-learning AI system analyses your data and processes and usually shows the first quick wins on day one. Only what shows up in the profit and loss account and the balance sheet counts.
For owners, private equity firms and family offices. And the best preparation, should you decide to sell later.
Fees
Our fee combines a monthly retainer with a success fee that only becomes due on completion of the transaction. This way we share the risk with you.
We agree the exact structure with you individually. It depends on the size of the transaction, its complexity and the type of process chosen. You will receive a specific proposal in the initial consultation, which is free of charge and without obligation.
Ready for a conversation?
Confidential, personal and without obligation. I will get back to you within 24 hours.